Critical Minerals: The same tonne cannot serve two strategies
Industrial policy is booking demand for minerals the physical economy may not deliver. Category teams still have to secure a slice of that contested tonne and put a price on what that security costs.
Western industrial strategy now speaks fluently in two languages: money and carbon. It is far less fluent in a third — the mineral cost of the ambitions it has already announced. Grids, electric vehicles, data centers, munitions and housing programs are treated as parallel national projects.
In the ground, and in the plant that turns rock into usable metal, they compete for the same physical flow.
Amanda van Dyke put the problem cleanly in The Mineral Footprint (7 September 2026). Governments have built an apparatus of industrial strategy around dollars and CO₂. What is largely absent is whether the physical economy can cash the cheque: tonnes, earth moved, energy and chemistry, industrial plant, and time. Minerals, she writes, are not an abstract input. They are finite flows from particular deposits, in particular countries, at particular grades. The same tonne of copper cannot simultaneously serve a transmission line, a Virginia data center, a German vehicle and a missile system.
That sentence is directionally right. It is not a law of physics. Markets adapt. The question for category strategy is whether adaptation arrives in the physical form, the specification and the time the plant actually needs.
That is not a mining essay. It is a procurement problem. Once a processing plant is full, late buyers do not simply pay more and get the metal. They wait. They substitute. Or they go without. Policy that ignores that allocation is not strategy. It is an unpaid option on someone else’s contracted supply.
2. Industrial Policy is now a supply-chain instrument
The last five years have moved critical minerals from the appendix of climate papers into the center of trade, defense and industrial law. The EU Critical Raw Materials Act still holds its 2030 benchmarks: 10 percent domestic extraction, 40 percent domestic processing, 25 percent recycling, and no more than 65 percent of any strategic raw material from a single third country at any processing stage. The United States has treated copper and other minerals as tariff, stockpile and allied-content problems. Canada is no longer a swing supplier. It is a structural pillar of a North American chain that policy is trying to pull out of a processing system China spent twenty-five years building.
Constraint sits in processing, not only in the ground.
None of that makes a tonne appear. S&P Global puts the average lead time from discovery to production at 17.9 years for mines that started in 2020–23, up from 12.7 years fifteen years earlier. In copper, the International Copper Study Group’s 2025 Factbook records China at 45 percent of world refined output in 2024 — 12.4 million tonnes of 27.5 — and 51 percent of blister and anode. Asia’s share of refined production rose from 19 percent in 1990 to 61 percent in 2024. The 2026 miner-to-smelter treatment and refining benchmark settled at $0 per tonne, the lowest on record; spot charges then went negative, so smelters paid for the right to treat concentrate. The constraint is not a slogan about criticality. It is mine lead time, plant geography, and where the deliverable tonne sits.
2. What is actually constrained
Three constraints now bind at once, and they do not bind at the same point in every mineral.
- Time. A new mine is a decade-class object — 17.9 years on the S&P Global sample of mines that started in 2020–23. A new conversion hall, smelter or APT plant is shorter than that, and still longer than a one-year supply contract. Industrial policy that assumes 2030 processing targets will clear from projects not yet permitted is writing a date the plant schedule cannot honor.
- Form. Van Dyke’s split between earth moved and conversion energy is the buyer’s split between ore in the ground and metal a plant can run. The scarce form is not “mining” in every mineral. In uranium it is conversion and enrichment, not the mine — Cameco, with about 18 percent of world primary conversion capacity, remains selective in committing unencumbered UF6 capacity under long-term contracts. In copper in 2026 it is payable concentrate plus finished metal in the right region: smelting capacity outran mine feed until the treatment charge hit zero. Treating every critical mineral as if the bottleneck were the pit is how strategies miss the step that actually rations access.
- Claim. Official demand is no longer leftover commercial demand. Grid investment, AI power, vehicle platforms, defense stockpiles and domestic-content rules all want the same parent tonne. A category team that treats uncontracted requirement as “we will buy it on the exchange” assumes metal will be sitting there — in their specification, in their country, in the week they need it. Tariff-driven stock moves in 2025–26 showed that visible metal can change venue faster than a plant can change specification.
3. The scarce form is not the same in every mineral
The same pattern shows up in other minerals, at different nodes. The numbers below are not a complete market. They are enough to stop treating copper as the only worked example.
Tungsten illustrates a different bottleneck. China produced roughly 79 percent of global mine supply in 2025 and controls much of the intermediate APT and carbide market. Export restrictions and licensing requirements drove sharp price increases. A tooling manufacturer does not buy ore. It buys the intermediary form the market can actually ration.
Zinc shows the same pattern at a different node. Mine supply barely grew for much of the last decade while smelting capacity continued to expand. Treatment charges fell from $274 per tonne in 2023 to $80 in the 2025 benchmark, and by 2026 spot concentrate charges had turned negative as smelters competed for feed. The United States illustrates the distinction between resource and usable form: it exports much of its mined zinc as concentrate while importing the refined metal its manufacturers actually consume. The bottleneck is not the ore body. It is the conversion step between concentrate and metal. A galvanizer does not buy a zinc deposit. It buys refined zinc from a smelter with available capacity.
None of those numbers mint a spare tonne for a late buyer. They show where the rationing step sits: concentrate for copper and zinc, APT and carbide for tungsten, conversion for uranium. A contract written on the wrong form is not cover.
3. Markets adapt. Adaptation is not a spare tonne
Real markets do not treat one tonne as one frozen claim. They substitute, redesign, thrift, recycle, raise efficiency and, when price or shortage is severe enough, they destroy demand. Those mechanisms are part of category strategy. Leaving them out makes the argument sound more deterministic than the market is.
They also have limits, and the limits are the point. Substitution is rarely a drop-in: aluminum can replace copper in some conductors and not in others; a mill’s approved supplier list does not rewrite itself because another metal exists. Redesign and thrifting cut intensity per unit, over a product-cycle, not over a quarter. Recycling is a second mine, and a slow one — the EU’s own 25 percent recycling benchmark for 2030 exists because secondary metal does not appear when a speech is made. Efficiency gains reduce forced usage; they do not cancel an uncovered campaign this year. Demand destruction is not a sourcing tactic. It is a mill that stops, a project that slips, a line that is not switched on.
So the title still holds inside a planning horizon. Over a decade the economy will use less metal per unit of output, recover more scrap, and redesign some applications out of the tightest form. This year, grid, vehicle, data-center and defense programs can still write claims on the same deliverable tonne — same specification, same plant. Category work has to hold both facts: plan for adaptation, and do not treat adaptation as cover.
4. Category management has to change shape
In a balanced market, category management earns its keep on price, specification and supplier leverage. In a constrained market it earns its keep on access. The work still starts with the familiar category toolkit. What changes is the question. Price and leverage are not enough when the same tonne is already spoken for. The team has to say what physical form the plant must use, who else wants it, what can be substituted or recovered in time, and what it costs to hold a slice.
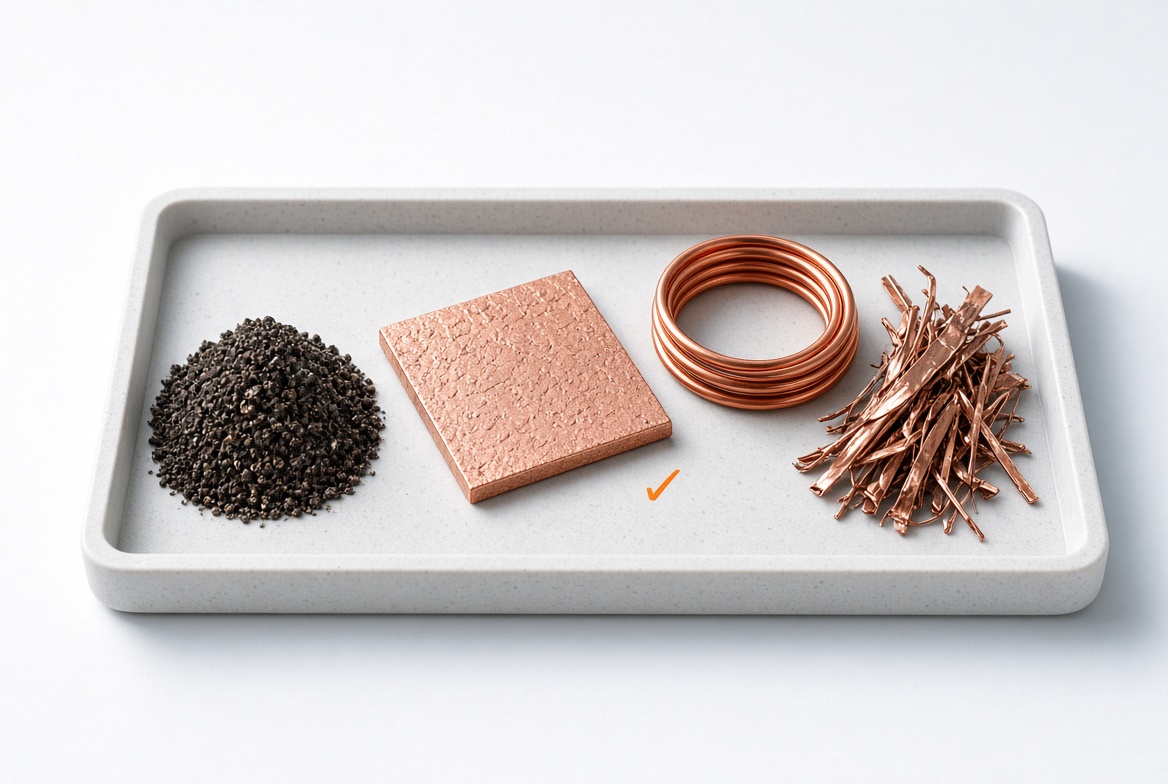
The category is the form the plant must use.
Very few buyers take title to raw metal. That is upstream operators. Most plants buy a semi-finished or finished form: cathode, rod, tube, cable, assemblies. Some large buyers step upstream and contract an earlier form in order to protect the plant. They are not separate categories the buyer can invent. A utility that also owns a cable plant is two category playbooks, not one “copper strategy.” The generation business is forced to use specified cable or fuel. The mill is forced to use rod. Different form, different suppliers, different meaning of running out. One combined copper number will hide that the grid can be covered while the mill is not.
5. Procurement secures allocation. It does not create tonnes
Securing a claim on a contested tonne is not something a dashboard solves. Off-take agreements, preferred-customer status, inventory and contract structure improve the probability of access. They cannot create metal that does not exist — or processing capacity that is already allocated. Some shortages cannot be contracted away. Category skill still matters. It does not mint a tonne.
Business requirements have to be written as forced usage, plus a specification and a definition of what “running out” means: the mill stops, an outage slips, or a new line cannot be switched on. That is not the same as an annual volume in a budget line. Cover is how many days or weeks of forced usage are already secured. Where substitution, scrap or redesign is real, it belongs in the requirement as an accepted alternative form — with a date. An unproven substitute is not cover.
Supply-market analysis has to separate three things. Where the metal was mined. Where it was processed. Which tariff border it must cross. Those are different risks. Take a Chilean cathode, refined in China, sitting in a US warehouse. That is one parcel of copper. A USMCA producer already on the mill’s approved list is another. Both are copper. They are not the same supply. The first can be stranded by a tariff or a supplier list. The second can run the mill this month.
Sourcing strategy under constraint is early off-take, locking a named producer’s brand — the registered quality the mill will accept, and the allocation the producer cannot quietly give to someone else — plus take-or-pay, optional volume and preferred-customer status. Those are priced, not described. Brand here is not a logo preference. It is the producer name on the approved list and on the warrant. Unlisted metal may still be copper. It is not cover.
How suppliers rank their customers is how capacity is rationed when the plant is full; treating supplier relationships as a quarterly scorecard is how a buyer discovers, too late, that they are a transactional account.
Contracts then must match the form the plant is forced to use. A cable-maker that has contracted cathode but needs rod is not covered. The paperwork is describing the wrong form of the metal. Those instruments raise the odds that this buyer is on the allocation list. They do not add concentrate, conversion or finished metal to the system. When the plant is full, preferred status decides who waits less. It does not decide whether the plant exists.
6. Four tools already exist. They do not all answer the same question
Readers will reasonably ask why this should not stop at risk-adjusted sourcing, real-options analysis, resilience-weighted inventory, or supply-assurance metrics. Those tools are not discarded. Each already does a job a commercial security ledger should not pretend to do.
- Risk-adjusted sourcing helps select among qualified suppliers. It does not price the commercial value of the security position already held.
- Real-options analysis helps value flexibility. Most boards will not run a volatility model on a weekly metals position, and an option value is not a measure of the posture already held.
- Resilience-weighted inventory sizes a buffer from disruption probability and time-to-recover. However, it is silent on the premium already paid in term contracts, and on origin or policy adders.
- Supply-assurance metrics — the scorecard is the plant’s control panel. It is not a dollar figure operations and finance share. “Ninety-five percent covered” can still be the wrong form of the metal.
The gap those tools leave is commercial. What did we pay for term cover versus today’s short-term market price? What does the inventory we chose to hold cost to carry? What extra did we pay for origin or policy? A Total Cost of Security (TCS)™ scorecard puts those three on one page — the annual cost of contracted cover plus physical buffer; what yesterdays contracts are worth against today’s market price; whether that position pays for itself; and the market price at which it breaks even. Use it to defend the position you have chosen to hold. Do not use it as a disruption model, an option pricer, a source-ranking tool or a plant scorecard. Those jobs stay with the tools built for them. The instruction is not “make the TCS number as small as possible.” A negative TCS versus the short-term market is the cost of not living hand-to-mouth. In a tight, policy-split market that cost can be the rational price of keeping a plant running.
7. Two scorecards, one physical fact
Van Dyke’s Mineral Footprint and TCS start from the same sentence: a category strategy that is silent on minerals will fail. They are complementary. They must not be treated as the same tool. They do different jobs.
The Footprint is a planning scorecard for a state or a program. It asks what the announced build-out consumes in the device, in the kit around it, and in the wider system. How much earth must move. What energy and chemistry the processing step burns. What substitution, scrap and redesign can take off that bill, and when. It refuses a single “mineral index,” because weighting scarcity, country risk and disturbance is a political act. Its question is simple. Can the physical economy cash this strategy at all?
Footprint counts the earth. TCS prices the slice.
TCS is a supply security scorecard for one category playbook. It takes the physical limit as given — the metal is finite and already spoken for — and asks what it costs this company to hold a slice of it. The questions stay the same across minerals. The settings do not. Nuclear fuel is a worked case because it has a clear short-term price, a clear term market and a visible processing bottleneck. Copper, tungsten, zinc, nickel and others qualify on the same test: a short-term price and a term market. Not because they resemble reactors. Each mineral needs its own settings for the form that buyer actually purchases.
The two scorecards work together. Industrial strategy needs the Footprint so it stops announcing tonnes the plant cannot produce. The company needs category research plus a commercial scorecard so it stops treating policy alignment as free resilience. An allied supply contract can improve where the metal comes from and still be a poor deal if the extra price and the cash tied up in inventory exceed the value versus today’s market. That is not a reason to ignore policy. It is a reason to price it.
8. Price the slice you actually buy
Any critical mineral with a short-term market and a term market can support a supply security scorecard. The principle does not change. The settings do. Copper does not inherit a nuclear operator’s inventory policy, and uranium does not inherit copper’s warehouse mechanics. What transfers is the commercial question.
What did yesterdays contracts create versus today’s short-term market? What does security cost this year: contract premium, inventory carrying cost, and any origin or policy premium? Is that position worth defending if market prices move against it?
Those questions do not replace risk-adjusted sourcing, options analysis, inventory design or supply-assurance metrics. They sit beside them. One set of tools secures access. The other explains what that access costs.
Companies seeking resilience should stop waiting for a national mineral strategy to clear their requisition. Identify the mineral that matters. Define the form the plant must consume. Recognize where substitution, recycling and redesign are genuinely available, and when. Then secure the contracts, producers, processing routes and buffer stock required to keep the operation running.
Industrial policy can create demand. Procurement can improve access. Neither can spend the same tonne twice.
Nuff said …
Further reading: TCS Prism™ · TCS Engine · TCS Advisory · The Mineral Footprint — Amanda van Dyke.
Sources: van Dyke, The Mineral Footprint, 7 Sept 2026; EU CRMA Art. 5 benchmarks (10 / 40 / 25 / 65); ICSG World Copper Factbook 2025 (China 45% refined output 2024; Asia refined share 19% in 1990, 61% in 2024); S&P Global mine lead times 17.9 years for 2020–23 starts; 2026 copper TC/RC benchmark $0 (Asia Copper Week settlement reporting); USGS / Metal Tech News tungsten mine share 2025; Reuters 29 Apr 2026 on APT prices and China tungsten export list; Fastmarkets 8 Sept 2026 zinc spot TCs CIF China; Nexa 2025 20-F exhibit on 2025 zinc benchmark TC $80/t; Cameco 2025 AIF (c. 18% world primary conversion); ILZSG zinc 2025 review; Purchasing Practice framework pages as linked. This article is management information, not investment, legal or procurement advice for a named category.